What the New Appraisal Rules Mean for Your Home Sale (And How You Win)
By Bridget Morrissey
If you’ve caught wind of recent real estate headlines, you might have heard whispers about major overhaul rules hitting home appraisals. Rumors often spread fast in housing: Are appraisal guidelines getting stricter? Are home values going to take a hit? Should we wait to sell?
Let’s clear the air right away: No, appraisals are not designed to tank your home value.
Appraisals aren’t becoming harder—they are becoming substantially more detailed. If you know how the new process works and prepare accordingly, this change can actually work in your favor.
Here is what is changing, how it affects your closing timeline, and what we do proactively to protect your equity.
What Changed? Meet the New Appraisal Standard (UAD 3.6)
Fannie Mae and Freddie Mac—the government-sponsored enterprises that back the majority of residential mortgages in the U.S.—have overhauled the standard appraisal reporting system.
Historically, appraisers relied on familiar legacy forms (such as the standard Form 1004 for single-family homes or Form 1073 for condominiums). Under the updated Uniform Appraisal Dataset (UAD 3.6 / URAR framework), those legacy forms are being replaced by a dynamic, data-intensive digital report.
The appraiser’s core objective hasn’t changed: they are still tasked with estimating fair market value. What has changed is the level of granular proof required:
-
Standardized Condition & Quality Ratings: Rather than broad generalizations, appraisers must assign standardized, evidence-backed ratings to individual areas of the home.
-
Granular Upgrade Tracking: Dedicated, line-item evaluation fields now specifically capture updates to kitchens, primary and guest baths, mechanical systems, roofs, and structural improvements.
-
Expanded Feature Audits: Specific standardized sections evaluate accessory dwelling units (ADUs), detached outbuildings, owned vs. leased solar setups, views, and specific architectural elements.
-
Extensive Photo Documentation: Appraisers are now required to submit an exhaustive photographic record supporting every single rating they assign.
In simple terms: Vague estimates are out; verified documentation is in.
The Transition Period: What to Expect on Closing Timelines
While these rules roll out nationwide, not every mortgage lender shifts overnight. Fannie Mae and Freddie Mac granted qualified lenders a transition window, meaning full mandatory adoption spans across the industry into spring (with legacy exceptions running until mid-May).
Because some lenders have fully adopted the new 3.6 format while others are still running legacy paperwork, here is what sellers and buyers need to keep in mind:
-
Varying Turnaround Times: In-depth digital reports require significantly more data entry and photo auditing from appraisers. During the initial rollout, expect appraisal turnarounds to occasionally add a brief buffer—sometimes an extra 1 to 2 weeks depending on the buyer’s lender.
-
Lender Coordination is Critical: When vetting offers on your home, we don’t just look at purchase price; we verify the buyer’s financing timeline, lender readiness, and how quickly their appraisal team is processing files.
How Proper Preparation Puts Money in Your Pocket
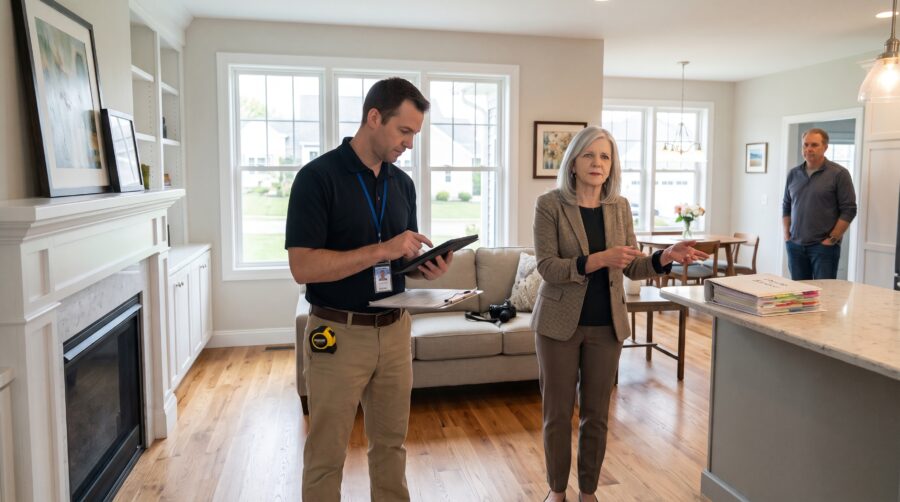
Because the new format rewards meticulous detail, the seller who simply unlocks the front door and hopes the appraiser notices their $60,000 remodel is leaving money on the table. If an appraiser doesn’t have concrete proof of what lies behind the walls or under the floors, they can’t give you credit for it.
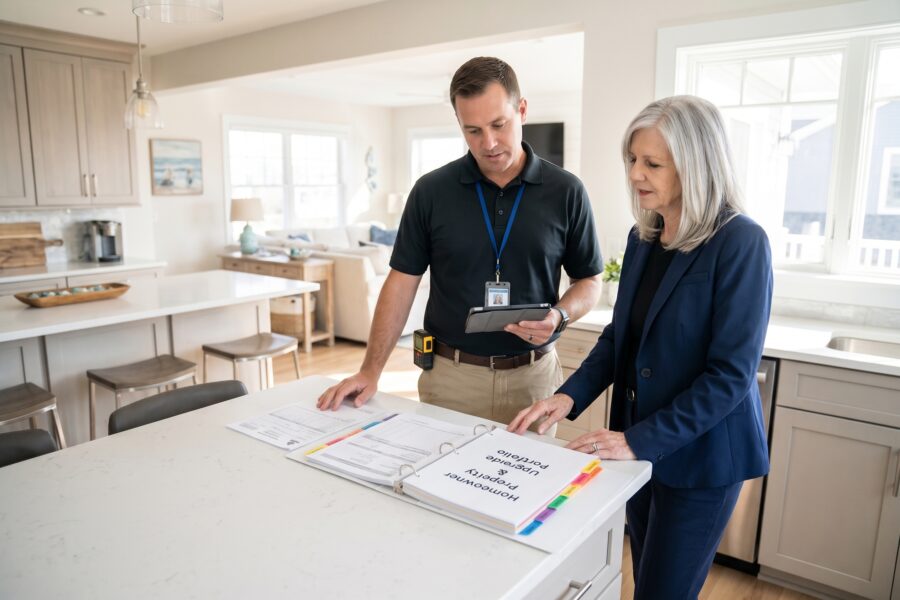
To ensure your home appraises for every dollar it deserves, we assemble a comprehensive Property Portfolio & Appraisal Packet before the appraiser ever steps across the threshold:
-
Itemized Capital Improvements: A detailed breakdown of every upgrade, major repair, and renovation you’ve completed—including dates, scope of work, and contractor receipts.
-
System & Roof Certifications: Proof of age and recent servicing for your HVAC, water heater, electrical panels, and roofing.
-
Permits & Architectural Plans: Valid permits for finished basements, additions, and structural changes to ensure your square footage is recognized and valued properly.
-
Solar & Energy Documentation: Explicit documentation showing whether solar panels or energy-efficient heat pumps are owned free-and-clear or financed/leased, preventing last-minute financing roadblocks.
By providing the appraiser with an organized, factual packet, we eliminate guesswork, speed up their on-site inspection, and build an airtight defense for your contract price.
A Quick Note on Financing Types (FHA vs. Conventional)
Getting ahead of appraisal details matters even more depending on your buyer’s loan program. On a conventional loan, an appraisal belongs strictly to that specific transaction. However, on government-backed loans like FHA, an appraisal stays logged with the property’s case number for up to 180 days.
If a deal derails due to an under-documented appraisal or unaddressed minor safety repair (like missing handrails or peeling paint), that valuation can follow the property to the next FHA buyer. Getting the details right the first time avoids costly delays and keeps negotiations entirely in your control.
The Bottom Line
Market shifts and regulatory updates don’t have to be stressful when you have the right strategy. The new appraisal rules are designed to reward homes that are well-maintained and clearly documented.
If you are thinking about selling this season or want to review which home improvements will yield the strongest return under today’s appraisal guidelines, reach out anytime. Let’s make sure your home’s full value gets the credit it deserves.